Running a business in Spain is a real opportunity for expats, but the accounting and tax system has its own logic, forms and deadlines. Most of the problems we see are not complicated: they come from assuming the rules work as they do at home, or from leaving paperwork until it is urgent. This article lists the mistakes we see most often and how to avoid them.
What are the key tax compliance errors expats should avoid in Spain?
Starting to trade before registering. The census registration with the Tax Agency (Modelo 036) must be filed before you start activities, carry out transactions or become obliged to withhold tax. Invoicing first and registering later creates problems that are avoidable.
Not updating the census registration. When the activity, the premises, the VAT position or the intra-community operations change, the census declaration has to be updated too.
Assuming there is a VAT threshold. Spain has no general VAT registration threshold for businesses established here. A business making supplies subject to VAT charges VAT from the first invoice. Our VAT guide explains why the 85,000 euro figure seen online does not apply in Spain.
Missing deadlines. Quarterly VAT returns are due in the first 20 days of April, July and October and the first 30 days of January. Corporate income tax and the annual accounts have their own calendar. Our first-year accounting checklist sets these out.
Misreporting income. Every source of income has to be declared in the right return, including income received abroad by people who are tax resident in Spain.
Which Social Security contributions are commonly overlooked by expat entrepreneurs?
- Self-employed contributions. Since 2023, people who work for themselves contribute according to their net annual income, choosing a contribution base from yearly tables and adjusting it if their income changes. Choosing a base that does not match your real income leads to adjustments later.
- Directors of their own company. Directors who manage their company and have effective control of it are generally included in the self-employed scheme (Article 305 of the General Social Security Law). Many owner-directors do not expect this.
- Employees. An employer must register with Social Security before starting activity and register each worker before they start work. Late registrations are one of the most common and most costly errors.
What are frequent VAT and invoice management mistakes made by expat businesses?
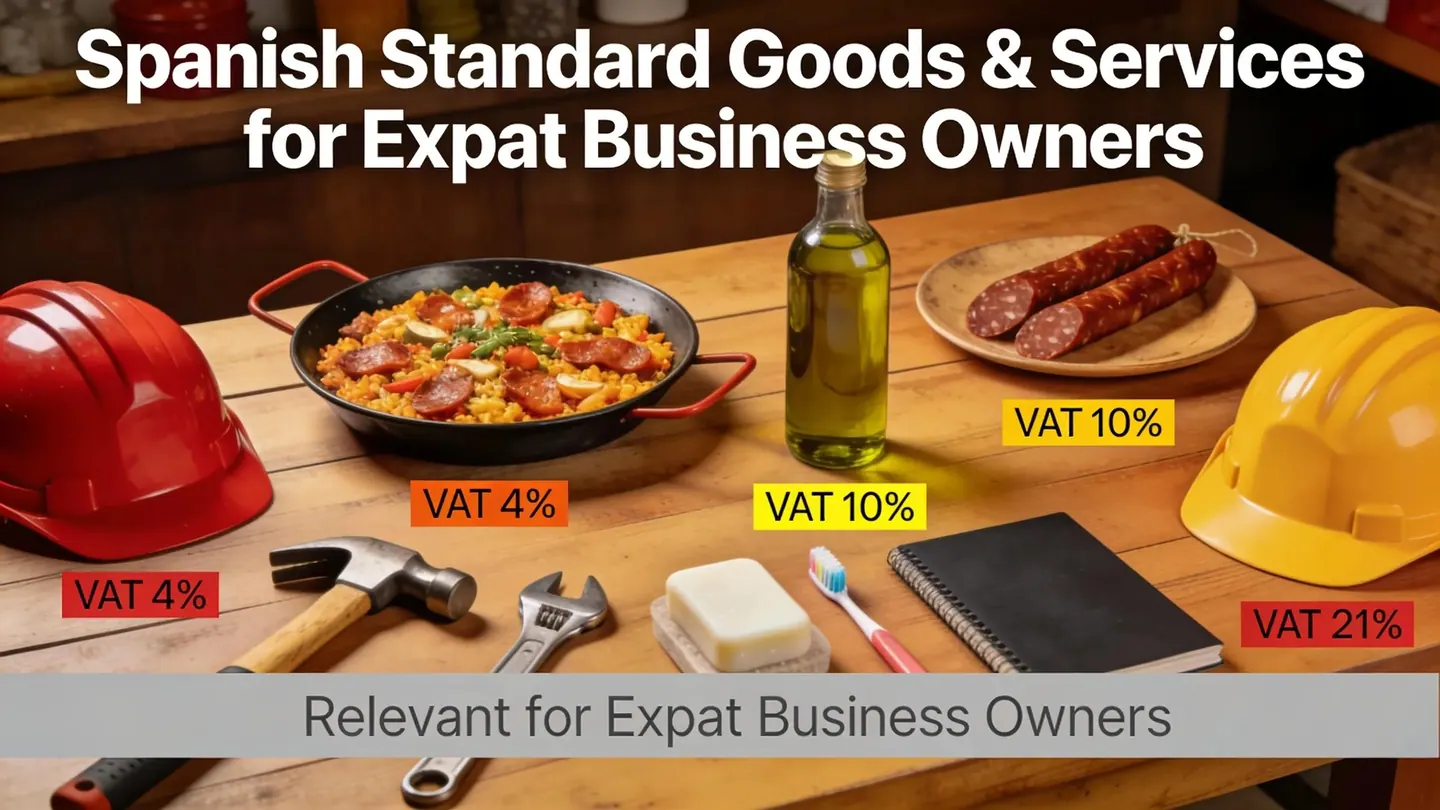
- Charging the wrong rate: Spain has a 21% general rate and reduced rates of 10% and 4% that depend on the exact product or service.
- Treating a sale to an EU business as exempt without checking the conditions, such as the customer’s valid EU VAT number and the recapitulative statement (Modelo 349).
- Deducting VAT on expenses that are not related to the business, or without a valid invoice.
- Filing the VAT return quarterly when the business is required to file monthly, or the reverse.
Building a simple, consistent invoicing process from the start avoids most of these.
What invoice recordkeeping errors lead to penalties in Spain?
Keeping invoices is a legal requirement, not just good practice. The Commercial Code requires businesses to keep their books, correspondence and supporting documents, properly organised, for six years from the last entry. Common errors are missing invoices for expenses, invoices without the customer’s or supplier’s tax number, and records scattered across e-mail, paper and apps. A single organised archive, digital or physical, solves most of them.
How do bookkeeping and financial reporting errors impact expat-run companies in Spain?
Poor bookkeeping hides the real financial position of the business and leads to poor decisions. The most common issues are entries made months late, bank accounts that are never reconciled and no view of cash flow. The Commercial Code requires orderly accounts that record all operations chronologically, so these are compliance issues as well as management ones. See our article on bookkeeping in Spain.
How can incorrect financial records affect tax audits and penalties?
If figures in the returns cannot be supported by the books and documents, the Tax Agency can adjust the tax due, charge late-payment interest and impose penalties. Under the General Tax Law, failing to pay tax that a correct return would have shown is an offence, and penalties range from 100% to 150% of the unpaid amount in very serious cases. Regular reconciliation and an adviser who reviews the figures before each return reduce this risk.
What legal and administrative pitfalls should expats avoid when registering their business in Spain?
- Choosing a structure by habit rather than by analysis: see our guide to choosing a business structure in Spain.
- Relying on out-of-date figures: for example, the minimum capital of a Spanish limited company has been 1 euro since Ley 18/2022, not 3,000 euros.
- Confusing the identification number for foreigners (NIE) with a residence or work permit.
- Leaving the company’s books and annual accounts until the end of the year.
What are the consequences of failing to meet administrative obligations?
Missed obligations lead to penalties, interest and, in serious cases, problems for the directors themselves. Companies must, for example, prepare their annual accounts within three months of the year end, have them approved within six months and file them with the Commercial Register within one month of approval. Keeping a calendar of these obligations and reviewing it with your adviser each quarter is the simplest protection.
Frequently asked questions
How far can the taxman go back in Spain?
As a general rule, the Tax Agency’s right to assess tax expires after four years (Article 66 of the General Tax Law), and the period can be interrupted, for example by an inspection. Separately, the Commercial Code requires businesses to keep their books and documents for six years.
Is the Spanish Social Security number the same as the NIE?
No. The NIE is the identification number for foreigners and, as a general rule, their tax number. The Social Security affiliation number is assigned separately by the General Treasury of Social Security when a person is first registered (affiliated) in the system.
How we can help
MMR Consultant is based in Málaga with offices in Marbella. Our accounting, tax and payroll teams help expat-run businesses keep their registrations, books and returns in order. Contact us for a review.
Sources
Checked on 14 October 2026.
- Agencia Tributaria, Modelo 036 frequently asked questions.
- Seguridad Social, contribution system for self-employed workers based on net income.
- Boletín Oficial del Estado, General Social Security Law, Article 305.
- Boletín Oficial del Estado, Social Security registration regulation (Royal Decree 84/1996), Articles 5, 21 and 32 (employer and worker registration; Social Security number).
- Boletín Oficial del Estado, VAT Regulation, Article 71, and VAT Law, Articles 25, 90, 91 and 120.
- Boletín Oficial del Estado, Commercial Code, Articles 25 and 30.
- Boletín Oficial del Estado, General Tax Law, Articles 66 and 191.
- Boletín Oficial del Estado, Capital Companies Law, Articles 4, 164, 253 and 279.
This article is general information, not tax advice for your case.